


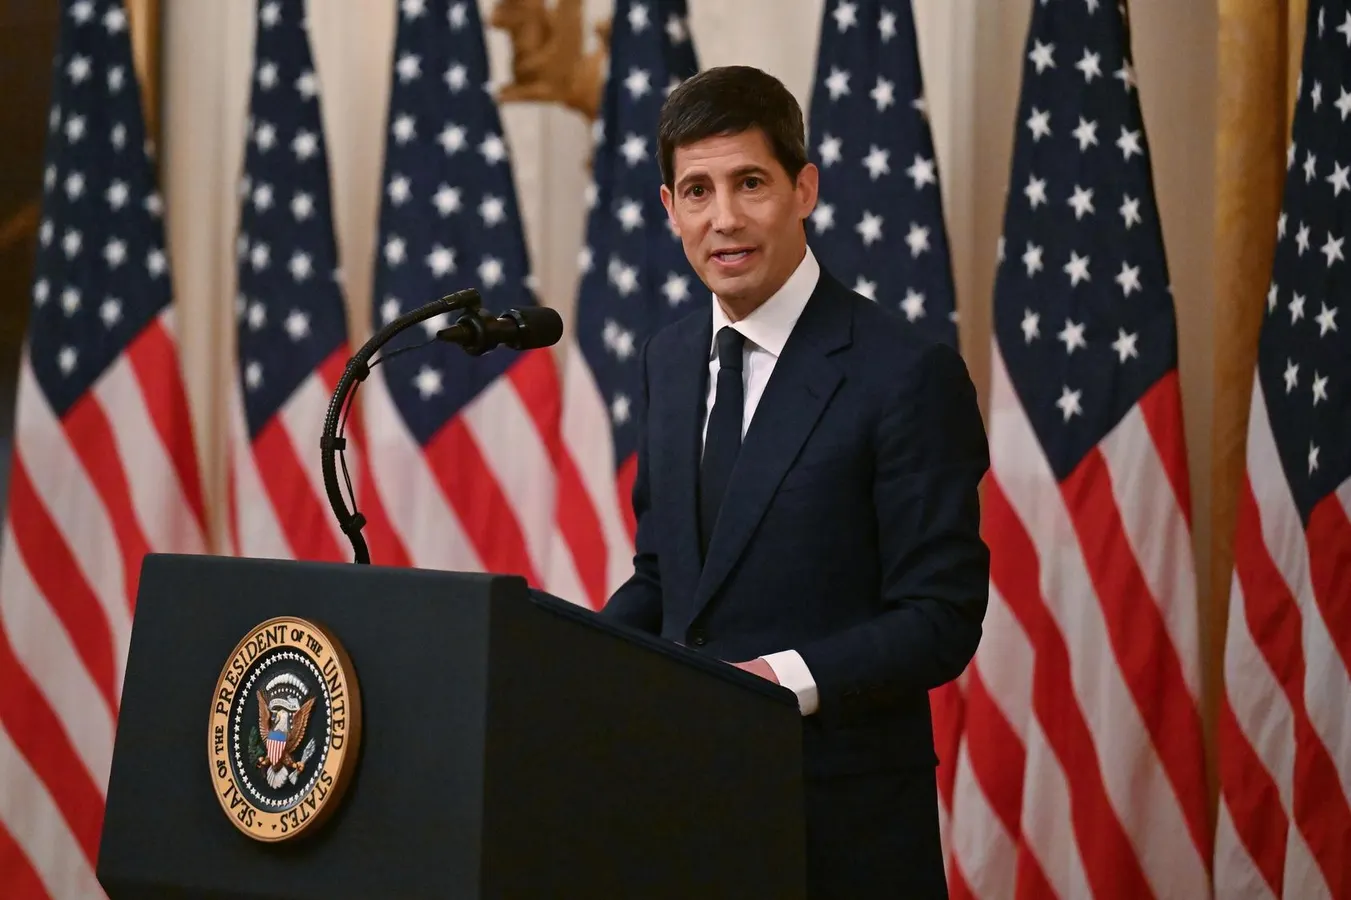

WASHINGTON, DC – MAY 22: Chairman of the Federal Reserve Kevin Warsh delivers remarks after being sworn in during a swearing-in ceremony in the East Room of the White House on May 22, 2026 in Washington, DC. Warsh succeeds Jerome Powell, who served as Chair for eight years. (Photo by Roberto Schmidt/Getty Images)
Getty Images
It probably seems like the Federal Reserve takes its role very seriously – with a staff of about 800 economists, among a total staff of 24,000. About 400 of these economists report directly to the Board of Governors itself, in Washington DC. We all know that they review dozens if not hundreds of economic indicators, resulting in minutia of policy differentiation that can take the form of a small change in a single sentence.
But, I will argue here that all of this central-planning theater is actually just a ridiculous clownshow, proof that even the Best and Brightest (a term I use with full sincerity when referring to Chairman Kevin Warsh, who really is as impressive as anyone could wish for) inevitably descend into bureaucratic idiocy.
Recently, we looked at the most basic question, “What Is Inflation?,” a topic that we wrote a whole book about in 2022, because we knew the 400+ economists at the Federal Reserve couldn’t answer this question adequately.
We summarized our argument as: Prices go up and down for a lot of reasons, which we can separate into two basic categories: “Non-Monetary” effects, and “Monetary” effects. The “Non-Monetary” effects are everything that might make prices go up and down, within the context of stable currency value. Basically this is supply and demand, and longer-term factors like productivity.
Let’s just focus on these “Non-Monetary” factors for now. There is actually a whole school of economics, loosely known as Keynesianism, which does exactly this. Here is Wikipedia’s summary of a giant pile of economic argle-bargle known as “Keynesian economics.”
Keynesian economics are the various macroeconomic theories and models of how aggregate demand (total spending in the economy) strongly influences economic output and inflation.
To simplify, individual prices can go up and down due to supply and demand for individual goods and services; and sometimes broad economic conditions (basically recession and expansion) can influence prices in general, within the context of a currency of stable value.
Today, this translates into the idea (rendered graphically as the “Phillips Curve”), that a strong economy tends to have declining unemployment and rising prices (as measured in common CPI statistics), and a recession tends to have rising unemployment and falling prices.
In reality, there are all kinds of prices, going up and down all the time. As a general rule, when an economy is doing well, some prices (especially for manufactured goods like steel in the 1880s, or flat-screen TVs today) are going down due to increasing productivity; and some prices are going up, such as wages, services, and urban real estate. As typically measured by government statistical agencies, the overall result is commonly a gentle rise in the official CPI index.
Let’s look at an example. Between 1950 and 1970, Japan’s nominal GDP rose by about 1,500%. A sixteen-times expansion in twenty years. Wages rose alongside. I bet that was fun. There was some population growth, but nominal per-capita national income (pretty close to personal income, i.e., wages) rose by 1,427%, a growth rate of 14.6% per year. Imagine your income rising 15x in the space of 20 years.
During 1950-1970, Japan’s Consumer Price Index rose about 155%. 2.5x higher. It works out to 4.8% compounded.
See, it works. Economic expansion really does lead to higher wages, and higher prices (as expressed by Japan’s official CPI). Go Keynesianism! Hooray Bill Phillips!
During this period, the yen was pegged to the dollar in the context of the Bretton Woods System. The official rate was 360 yen per dollar, and this was assiduously maintained. Since the dollar was also pegged to gold at $35/oz. (889 milligrams per dollar), this meant that the yen was also pegged to gold, at 12,600 yen per ounce (or 2.47 milligrams of gold.) The yen was originally worth one dollar, when introduced in 1871, but had a hard time especially in the immediate postwar period.
Gold served as a practical proxy for Stable Monetary Value, a role it had served literally since the beginnings of human history. By all measures, it was serving this role well in the 1950 and 1960s. Commodity prices, in terms of gold, were flat as a board. There was no evidence that gold was going up and down in value, in some irregular and destructive manner. Rather, it was serving, as hoped and intended, as a Universal Constant of Commerce, which is one reason why the Japanese – and German, and US – economies were able to do so well in those years.
In other words, we have a very good example here of “Non-Monetary” influences on prices, in the context of Stable Monetary Value. Wages went up a lot – 15x is a lot – and the CPI also went up, more than doubling during this time. There were no “stable prices” or “stable purchasing power.” That is not a thing that existed. But, the money was stable in value.
Now just imagine that you are living in Tokyo in 1964. The unemployment rate is 1.2% (not a typo). The economy, and your personal income, are growing around 15% a year. Higher wages naturally lead to higher costs for labor-intensive services, while rents and property prices are soaring along with personal income. The CPI is rising almost 5% per year, but so what, that is far behind your increases in wages. The prices of electric rice cookers and washing machines fall every year.
In short, everything is wonderful – and after sixty years of hindsight, no bad thing (except maybe some pollution problems) has been found to result from what was one of the greatest success stories of the century.
Now think about this. The Bank of Japan was founded in 1882. It was, in 1964, the sole issuer and manager of the currency. The Bank of Japan saw this meteoric rise in wages, and persistent rise in the CPI, and pinch-me-I’m-dreaming unemployment rate, and said: To Get Rich Is Glorious. It did nothing, except maintain the policy of keeping the yen at 360 per dollar or 12,600 per ounce of gold, same thing.
This did not require 400 economists. And, it worked.
Now look at all the stuff the Federal Reserve talks about today. Can you understand why I call this a clownshow?





Leave a comment