


The government of Venezuela has defaulted 11 times since 1800. To believe that the next loan will be different is to play the role of Charlie Brown kicking Lucy’s football.
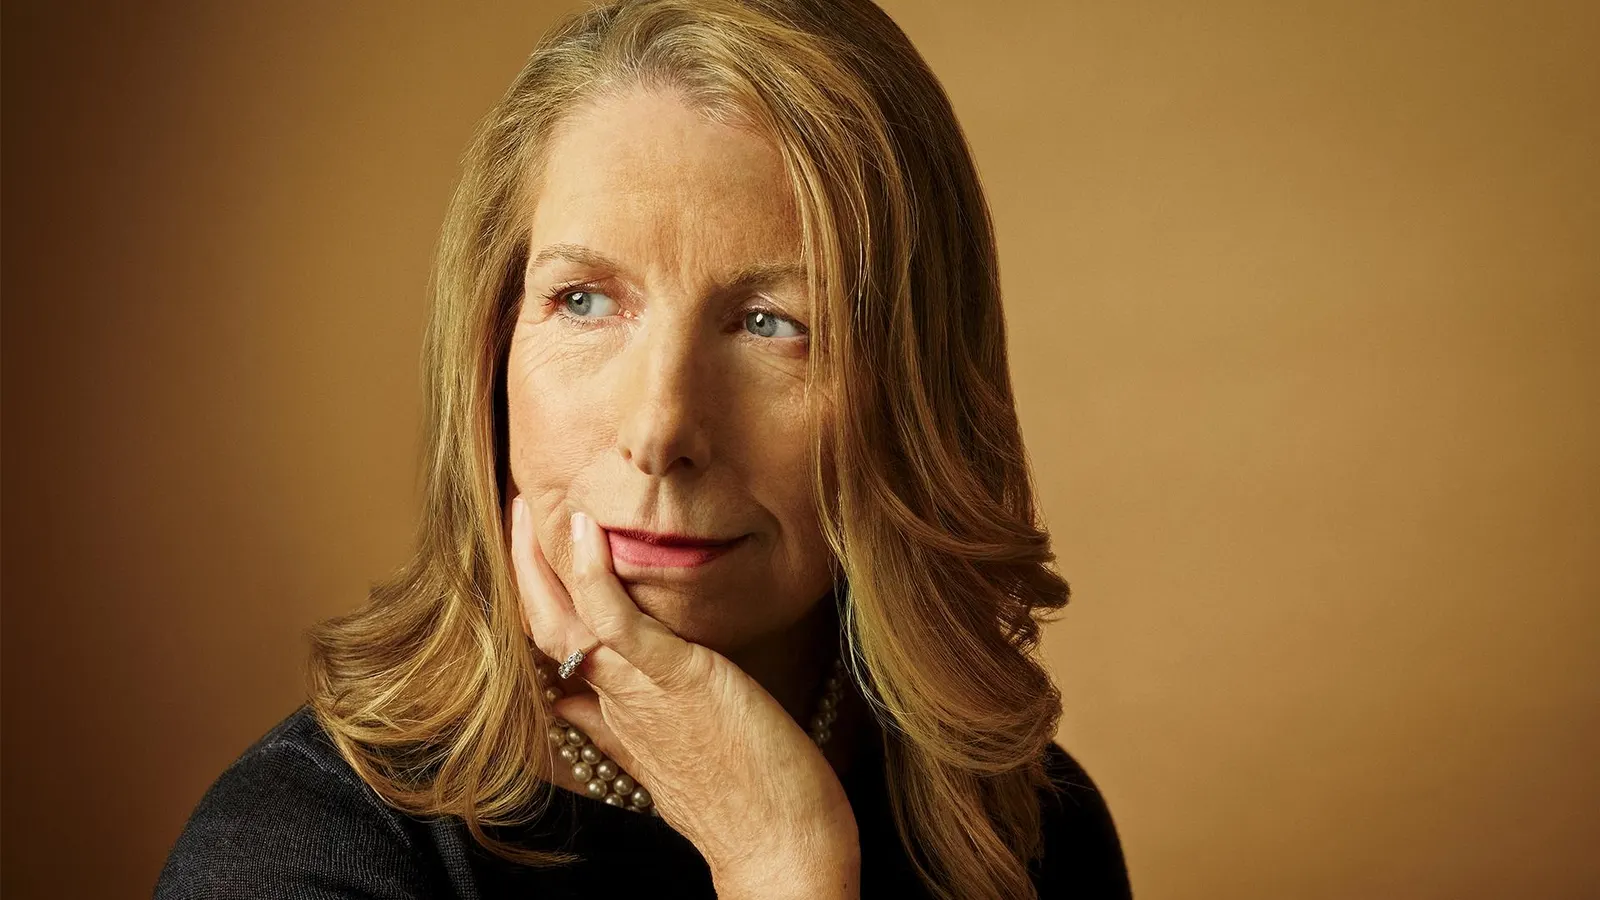
Meet Tina Vandersteel, emerging-markets bond guru in the Boston office of Grantham, Mayo, Van Otterloo. She has made money on Venezuelan bonds. Also on lending to Russia and to the planet’s worst-managed oil company. She has investors’ capital in Belarus, El Salvador and Uzbekistan.
Vandersteel oversees $10 billion, much of it tucked away in separately managed accounts. The most visible portion is the $2.2 billion GMO Emerging Country Debt Fund, which she took over in 2016 at the midpoint of a career that started, in 1990, fresh off an economics degree, evaluating Third World debt at the predecessor to JPMorgan Chase.
Under Vandersteel the GMO fund has had unusual success in a difficult market for fixed income. Over the past decade Vanguard has eked out 1.1% a year on its fund holding medium-term U.S. Treasuries and only a little more, 3%, on its index fund holding government bonds in emerging markets. Her fund has delivered 6.4% a year, net of 0.54% in fees.
How do you make money lending to potential defaulters? Mostly by trading. “It’s a shockingly inefficient space,” she says.
Venezuela? Its bonds got as low as 6 cents on the dollar. At this price they were an interesting long shot, worth putting in the portfolio for amusement. Post-Maduro, the fund’s Venezuela bonds have recovered to between 37 and 54 cents.
[id=NaN]
How to play it
By William Baldwin
The U.S. dollar is richly priced, having briskly appreciated in the past decade against emerging-market currencies like the Brazilian real and the Polish zloty. Want to bet on a reversal by owning securities from faraway places? Vanguard Emerging Markets Government Bond doesn’t quite do the trick because it buys only hard-currency debt. Vandersteel’s GMO Emerging Country Debt fund does own local-currency bonds but hedges away most of the foreign exchange exposure (and, it should be noted, requires $1 million at the firm). The best option, if you don’t mind equity risk, is Vanguard FTSE Emerging Markets Index, which holds 6,300 stocks for an annual fee of 0.06%.
William Baldwin is Forbes’ Investment Strategies columnist.
As for Russia, it’s hard to remember now that this debtor was, until the week before it invaded its neighbor, considered investment-grade. Vandersteel’s fund bought some of the chancy paper before the war but covered the risk by
simultaneously buying a credit default swap. It thereby locked in a small gain that paid off when Russia defaulted and the insurance kicked in.
Shunning most corporate debt, the GMO fund prefers sovereign and sovereign-adjacent paper—the latter being debt that has an implicit government guarantee. Petróleos Mexicanos is an interesting case. This outfit features decrepit infrastructure and an inefficient staff that can lose money even when the price of oil shoots up. A glance at the financials scares away most bond buyers, resulting in a handsome yield advantage over Mexico’s sovereign debt. GMO’s take: Recent bailouts by the government indicate that the country won’t tolerate a default at the national oil company. The fund has $84 million of Pemex IOUs.
“Typically, bonds that are cheap stay cheap for years, and we just sit on them,” Vandersteel says. Counterexample: Mexican government bonds due in 2114 and payable in pounds. Vandersteel was sitting on a pile of them four years ago when a crash in British government bond prices made the Mexican bonds worth less. But their price momentarily stayed put. “In this case, overnight, or in the course of a morning,” Vandersteel says, the Mexican sterling debt “went from very cheap to super-rich, because nobody was paying attention.”
The fund unloaded the overpriced sterling bonds, then bought them back when the market came to its senses. Says Vandersteel: “I spend 100% of my day thinking about this kind of stuff.”
Hearing blandishments from visiting finance ministers does not interest her. “I have no time to travel to countries. I sit at my desk, watching bond prices from 6:30 to 4.” She is quite the early bird. She is a competitive rower; at 57, she gets up at 3:50 a.m. to practice on the Charles River.
The emerging-country sector is not especially cheap at the moment. Vandersteel explains: Multiply by itself seven times an 8×8 matrix of how bond grades have historically drifted up or down over the space of a year. That yields a probability of default by 2033. Figure in a 25% recovery following default.
This exercise suggests emerging debt repayable in hard currencies (like dollars or pounds) will suffer a collective percentage point of annual principal loss, she says. Such debt is now yielding on average two points over U.S. Treasuries. Thus, the expected reward for taking a chance on sketchy borrowers is perhaps a point of incremental return. Good but not, by historical measures, terrific.
Then why should investors send capital to underdeveloped economies? Vandersteel offers two rationales. One is to put history aside and note that the pandemic pushed countries on the edge over it. With defaults behind it, the sector is perhaps poised for a few years of financial calm.
The other argument is that diversification, a good thing in a portfolio, comes naturally to emerging-market lenders. The GMO fund is dispersed across 69 countries. Unlike borrowers in the U.S. corporate junk market, these aren’t especially correlated. A coup in Uzbekistan isn’t going to precipitate a financial crisis in El Salvador.
International diversification pays for Vandersteel personally. When the Charles freezes over she repairs to a second home in Brazil and keeps up the sculling. When her daughter wanted tickets to a Martin Garrix concert, they went to a show in Florianópolis, paying, because the real is undervalued, less than half what they cost in Florida.
Now consider the lack of diversification in a typical U.S. investor’s bond portfolio. An awful lot of the lending is to a known deadbeat, the U.S. government. In 1933 it welched on a promise to repay debts in gold, replacing the metal with greenbacks that have since lost 96% of their purchasing power.
The next default may be a more subtle one, Vandersteel says, involving TIPS. Copycatting mischief that has been employed on more than one occasion by the Brazilian government, she says, Treasury could stiff you by fiddling with the inflation measure.
Our country’s balance sheet is pretty bleak, with government debt equal to 123% of annual economic output. That’s worse than in Belarus, El Salvador and Uzbekistan. Imagine: Your T-bonds go bad, but Uzbekistan pays. Could happen. Vandersteel: “Never say never in sovereign debt land.”




Leave a comment