


Sanctions aimed at squeezing Moscow’s revenues have instead helped drive up prices, making Russian crude more valuable
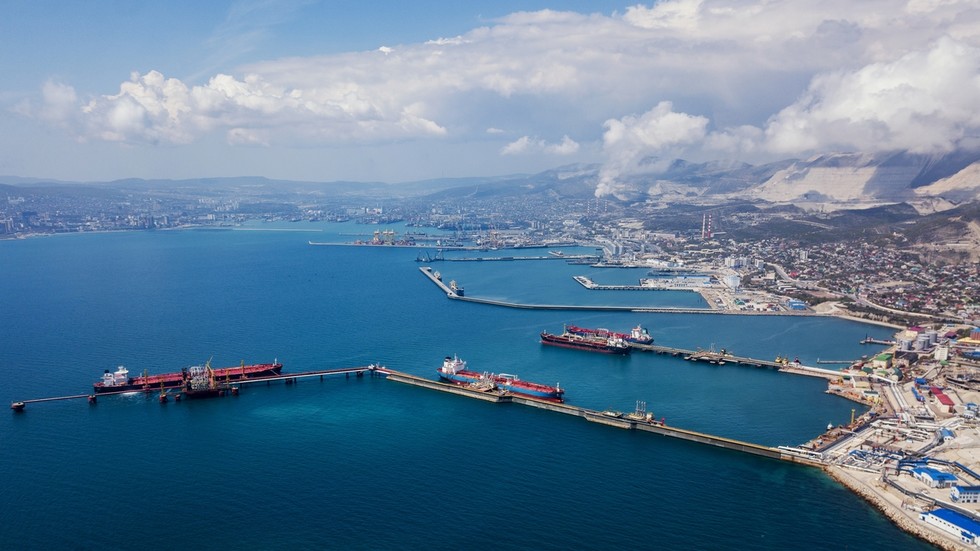
Nearly four years after Western governments set out to squeeze Russia’s oil revenues, Moscow is shipping crude worth more per week than at any point since the escalation of the Ukraine conflict in 2022.
The gross value of Russia’s seaborne crude exports surged to $2.75 billion in the week through September 27, the highest weekly figure in four years, according to tanker-tracking data compiled by Bloomberg. Shipments averaged 3.71 million barrels per day over the latest four weeks, their highest since early August.
The rebound exposes a central problem with the Western strategy. Sanctions were designed to keep Russian oil on the global market to avoid a supply shock while forcing Moscow to sell it more cheaply.
Instead, Russia rerouted crude from Europe to China, India, and other markets, built alternative shipping networks, and reduced its reliance on Western services. Now, soaring global prices fueled by the US-Israeli war on Iran are making those barrels more valuable.
The plan: Keep Russian oil flowing but slash Moscow’s earnings
When the West moved against Russian oil in 2022, it faced an obvious problem: Russia was too large an exporter to remove from the market without risking a surge in global prices.
The EU was also Moscow’s biggest oil market. Europe took more than half of Russia’s oil exports in 2021, while Russia was the EU’s largest crude supplier, accounting for roughly a quarter of its imports. China, by comparison, was Russia’s largest single-country buyer.
The EU banned most seaborne Russian crude imports in December 2022, while the G7-led bloc imposed a $60-per-barrel price cap. Western shipping, insurance, and other maritime services could still handle Russian crude, but only if it was sold below the ceiling. Sanctions on petroleum products followed in February 2023.
The logic was simple: cut Russia’s revenues without removing its oil from the global market. The strategy therefore depended on keeping Russian crude flowing while using Western dominance of shipping and insurance services to constrain its price.
The plan backfired.
What went wrong?
The $60 cap initially coincided with steep discounts on Russia’s flagship Urals crude. But Moscow gradually reduced its dependence on Western shipping and insurance services by which the ceiling was supposed to be enforced.
Even the Centre for Research on Energy and Clean Air (CREA) – a Helsinki-based research organization that has repeatedly advocated tougher sanctions on Moscow – now says the policy has “failed to impose a durable constraint on Russian crude export earnings.” It says the measure worked only for limited periods on Urals, while other grades and export channels were largely unaffected.
The EU repeatedly tightened the mechanism, lowering the ceiling first to $47.60 and then to $44.10 per barrel from February 2026. The latter was intended to remain 15% below the average market price for Urals.
Yet Urals averaged $60.22 a barrel in July – roughly $16 above the EU and UK ceiling. Russia’s ESPO crude, heavily oriented toward Asian buyers, has also consistently traded above both the old and new caps, according to CREA.
Brussels has responded by sanctioning hundreds of tankers, targeting traders, and tightening restrictions on third-country entities accused of helping Moscow circumvent the measures. Russian crude, however, continues to flow.
Four years later: Where is Russian oil going?
Russia did not stop selling oil when its biggest European customers turned away. It found other customers.
China and India emerged as the dominant destinations for Russian crude, while Türkiye also increased its role. In July alone, India imported $6.25 billion worth of Russian crude – a record high for a second consecutive month – while seaborne deliveries to China were 16% higher than a year earlier, according to CREA.
Russia also built up shipping capacity outside the traditional Western system. By June, sanctioned “shadow” tankers were carrying 66% of its seaborne crude exports, compared with just 31% aboard G7-linked vessels, CREA estimates.
Sanctions changed the routes, ships, and customers. They did not stop millions of barrels of Russian crude from reaching the global market.
Why is Russian oil worth more now?
The biggest twist has come not from Brussels or Washington, but from the Middle East. The US-Israeli war on Iran and disruption around the Strait of Hormuz have pushed global crude prices sharply higher, while attacks on regional energy infrastructure have further strained supplies.
The result is precisely the type of supply shock Western governments sought to avoid when designing the price cap – and Russia is among the producers benefiting from higher prices.
On a four-week basis, the gross value of Russia’s crude shipments has risen to $2.39 billion per week, up $290 million from the previous four-week period, according to Bloomberg.
The price shock has also complicated efforts to tighten the squeeze. Earlier this year, the EU considered a maritime-services ban that would have gone beyond the price cap by directly targeting Russia’s ability to ship oil. But soaring prices following the Hormuz disruption prompted a rethink over fears that squeezing Russian exports could worsen the global shortage, according to CREA.

The EU subsequently suspended automatic adjustments to its Russian crude price cap until July 2027, while retaining the option of an earlier review.
The dilemma is the same one Western governments faced in 2022: squeeze Russian supply too hard and global prices could rise further – making the barrels that still reach the market more valuable.
Not all barrels are created equal: The refinery factor
The surge in the value of Russia’s crude exports does not tell the whole story.
Ukrainian drone attacks have disrupted Russian refineries, reducing domestic processing and leaving more crude available for export. Moscow has also restricted diesel shipments to protect domestic supplies.
Russian oil-product loadings fell to 4.7 million tons in July, their lowest level on record and less than half the 9.6 million tons shipped a year earlier, according to CREA. Seaborne crude revenues, by contrast, rose 7%. Russia has also raised its 2026 crude-export forecast while cutting its outlook for refined-product shipments.
The crude boom is therefore being partly offset by weaker fuel exports. At the same time, reduced refinery activity is freeing up more unprocessed oil for shipment abroad – where higher global prices have increased its value.
Europe doubles down
Despite the limits exposed by the price-cap system, Western governments are continuing to tighten restrictions and pressing European states that still rely heavily on Russian energy to cut their remaining ties.
Slovakia and Hungary have resisted demands for a rapid cutoff, arguing that refineries, pipelines, and other infrastructure built around Russian supplies cannot simply be switched to alternatives overnight.
The dispute returned to the fore this week when German Foreign Minister Johann Wadephul traveled to Slovakia and urged it to move away from Russian oil and gas and increase pressure on Moscow.
Slovak Foreign Minister Juraj Blanar pushed back, saying the country’s infrastructure was built around Russian supplies and that an immediate cutoff would create “enormous problems.”
The West’s Catch-22
The West can sanction more tankers and traders, tighten enforcement, pressure remaining buyers and target third-country networks. The EU’s latest sanctions package added another 41 vessels to a list that already includes 632 ships and targeted entities in China, India, Türkiye, Kazakhstan, and the UAE.
But directly targeting Russian export volumes brings the original dilemma back into focus: the West kept Russian barrels on the market because it feared soaring oil prices – only for soaring oil prices to make those barrels more valuable.



Leave a comment