


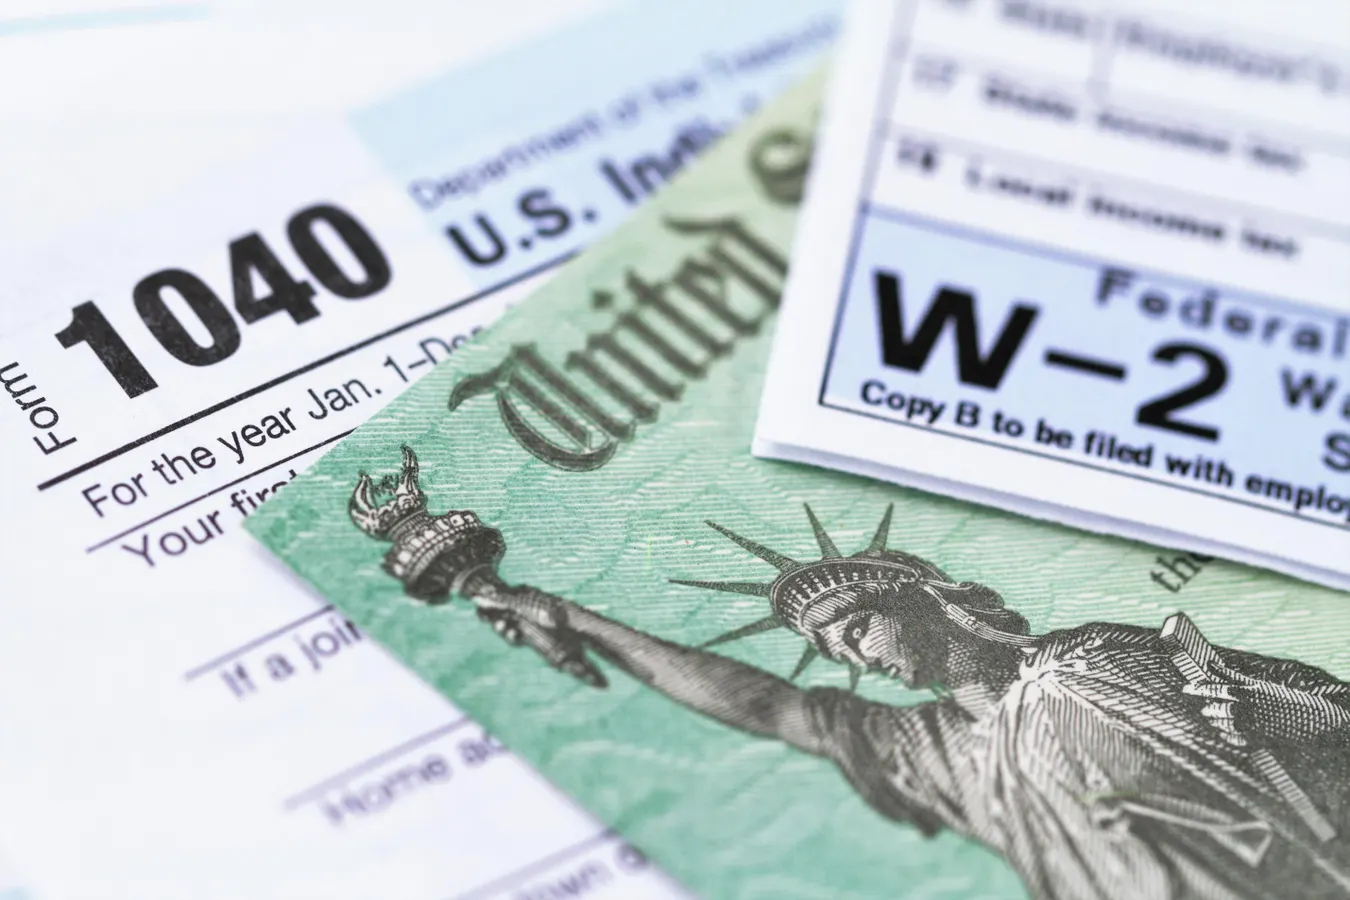

Every April, U.S. taxpayers become very familiar with the tax document known as the Form 1040 – the U.S. individual income tax return. Like most years, the IRS has updated this form for the 2026 tax year filing. However, it will now include a new question asking filers about their U.S. citizenship and their right to work in the U.S. legally. The IRS’s recently released draft is exactly that: a draft. It can still change in the coming months. However, this addition marks the first time the individual income tax return documents will ask filers about their citizenship and work status, and it is leading to questions and discussions about whether this is the time and place for such a question. Depending on how the final language shakes out, this single yes or no question could end up being a minor administrative footnote or a major shift in how the federal government collects, and potentially shares, personal information about the people who file a tax return.
Form 1040 – The Individual Income Tax Return
Ask the average taxpayer about the Form 1040, and they will likely depict it as a math problem that only their accountant can solve. It starts with the taxpayer reporting income, then subtracts deductions and applies credits to arrive at the refund amount (or balance due). Where it can be complicated is that there are rules that govern each line of the tax form, and every line (whether it be income, deductions, or credits) feeds into the end calculation of taxable income.
However, the 1040 has quietly grown into something broader than the means for a taxpayer to calculate and report their taxable income. For instance, the Form 1040 now asks whether the taxpayer has received, sold, or exchanged cryptocurrency during the year. The question does not ask for how much was bought or sold. Instead, it is an informational question that the IRS uses to construct a paper trail of a historically underreported asset class. Thus, the Form 1040 has become a place where the government gathers useful information that can then be used to enforce policy (not just calculate the taxpayer’s tax liability).
Federal income tax obligations are not limited to citizens, meaning that those working in the U.S. must file the Form 1040. Resident aliens generally follow the same rules as citizens. Working in the United States, regardless of immigration status, generally creates a tax obligation, and the proposed question sitting at the top of the form will now require an explicit affirmation of their status.
Why Would the IRS Want to Know Citizenship Status?
While the draft version of the Form 1040 was recently released, U.S. News reported in May that the IRS was considering a version of the form that would require taxpayers to disclose citizenship status in their returns. The version that surfaced in September asks a single yes or no question: “At the time you file your return, are you, and your spouse if filing jointly, a U.S. citizen, U.S. national, or an alien lawfully authorized to work in the U.S.?”.
The rationale for including this question is simple. Treasury and the IRS have proposed immigration eligibility restrictions on the refunded portions of several tax credits, including the earned income credit, the additional child tax credit, the American opportunity tax credit, and the adoption credit. A new draft Schedule 3-A tied to those credits would ask whether a taxpayer or spouse is a citizen, national, or qualified alien under federal benefits law.
If a benefit is restricted to citizens or certain lawfully present individuals, the IRS needs a way to verify eligibility. By including this question on Form 1040, this question can serve that purpose. Furthermore, in asking this question before the benefits are restricted, the government can have greater assurance that the taxpayers are responding truthfully.
What Are Potential Unintended Consequences Of Asking About Citizenship Status On The Form 1040?
Many taxpayers potentially must now face the difficult decision of reporting their citizenship status directly to the IRS. A key reason why this decision could be difficult for some taxpayers is that it is unclear what happens to the information once the IRS obtains it.
For instance, days before the draft form was released, the D.C. Circuit Court of Appeals upheld an injunction against an IRS procedure used to provide more than 47,000 taxpayer records to Immigration and Customs Enforcement. In particular, the court ruled that it could not ensure that these requests satisfied federal requirements governing disclosure of confidential tax information.
Federal tax privacy law restricts the situations when and where the IRS could release confidential tax return information to another governmental agency, and those restrictions would presumably still apply here. However, the D.C. Circuit Court of Appeals decision suggests that these restrictions may not be as impermeable as previously thought, and the Form 1040’s citizenship question might be a prime target for such information.
Furthermore, taxpayer advocates have argued that simply asking the question could discourage some immigrants from filing returns at all, according to LawCommentary. Put differently, anxiety over the potential transfer of this information may shape taxpayer behavior, resulting in depressed tax compliance and tax collections.
What Comes Next For The 2026 Form 1040?
While the Form 1040 draft is not finalized, it is possible (if not likely) that some citizenship question will be part of the final version of the form. If the language does, in fact, survive, taxpayers would first encounter it on returns filed this coming Spring of 2027 for their 2026 tax year. However, until the final version is released, it is still unclear as to whether this question will survive. Until then, taxpayers, tax professionals, and many non-citizen taxpayers are going to be left waiting for that final wording.





Leave a comment