


Topline
Market forecasts put the odds of the Fed hiking interest rates at Wednesday’s meeting at 90%, which could push up borrowing costs for consumers, particularly for credit-card balances and other variable-rate loans, as well as rates on new auto and mortgage loans.
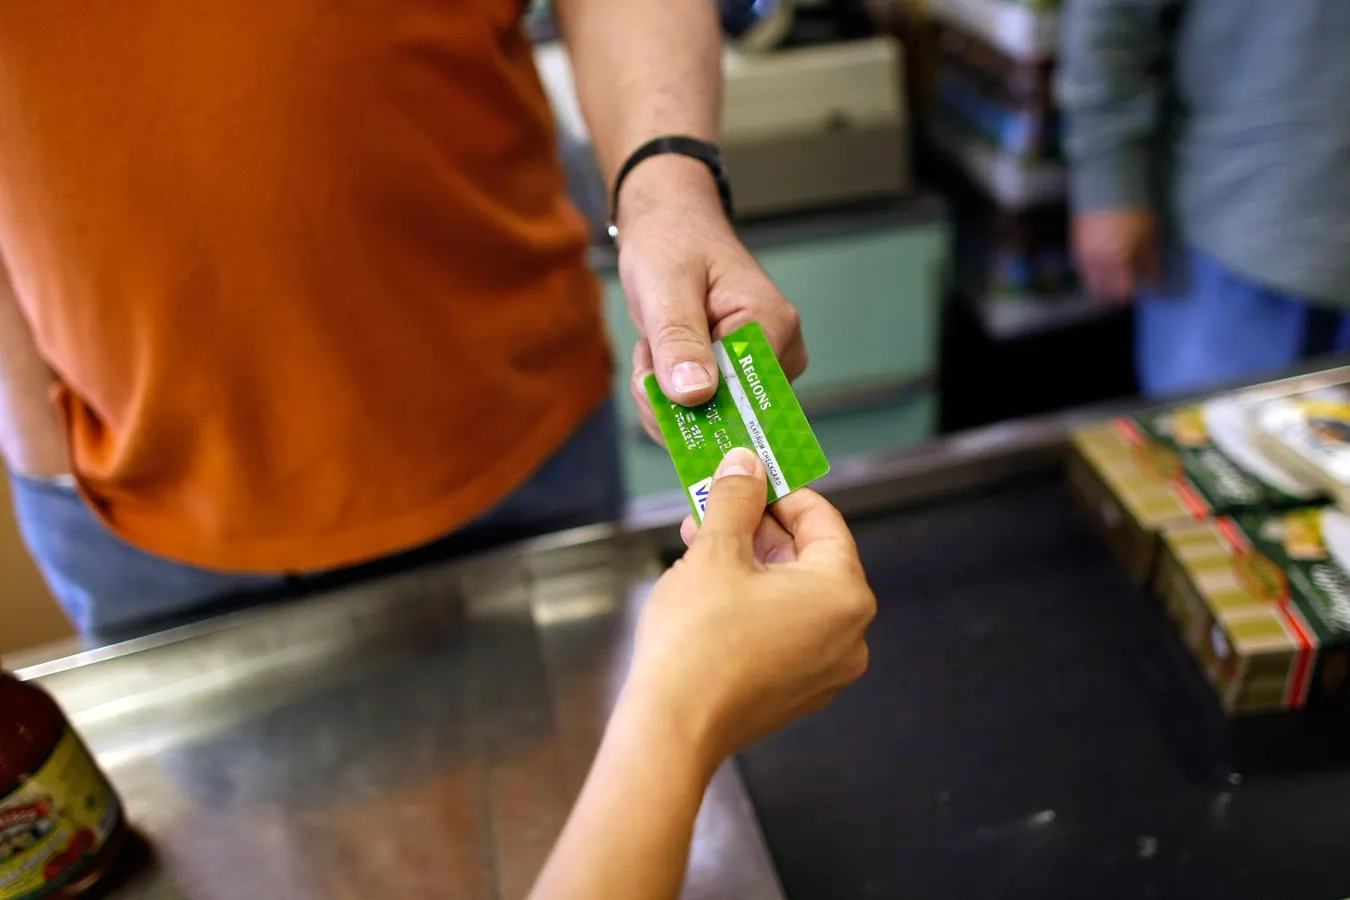
MIAMI – MAY 20: Yera Dominguez receives a credit card from a customer for payment at Lorenzo’s Italian Market on May 20, 2009 in Miami, Florida. (Photo by Joe Raedle/Getty Images)
Getty Images
Key Facts
The Fed is expected to raise its benchmark federal funds rate by a quarter percentage point to 3.75%-4% at its September meeting on Wednesday, which would be the first hike since July 2023.
An interest rate hike would raise borrowing costs for variable-rate credit cards and short-term loans, as well as keep car loans and mortgages expensive as a result of overall elevated lending costs.
If the Fed raises its benchmark federal funds rate by a quarter percentage point, credit card annual percentage rates will rise by 0.25%, which would bring average credit card interest rates to 25.21% and mean that for every $1,000 you owe, you would pay about $2.50 more in interest per year.
Variable-rate loans would also go up by around 0.25% within one or two billing cycles, and while fixed-debt contracts or mortgage rates would not automatically go up, it means home and auto loans will likely remain expensive if not rise.
A WalletHub analysis predicts that a 25-basis-point Fed rate hike would raise the average APR on a 48-month new car loan by 0.12%.
Adjustable-rate mortgages typically adjust once a year and home equity lines of credit adjust right away, meaning they would respond to the hike even though many of these housing loans follow long-term Treasury rates.
KEY BACKGROUND
The consumer price index rose 3.4% over the year in August, remaining unchanged from July, reflecting continued price pressures driven by high energy and gas prices. Gas prices had risen 3.9% during the month of August, and overall energy prices rose 16.3% compared to the previous year. These rising costs translate directly to shipping and manufacturing, which impacts non-energy sectors like food and services, driving the Fed to keep a close eye on inflation. The unemployment rate also remained unchanged at 4.1% in August, with employers adding 162,000 jobs, giving the Fed reason to prioritize inflation. Prices have been rising faster than average wages since April, and high fuel prices threaten to raise the price of many goods.
CRUCIAL QUOTE
“Credit card rates, which are above 20%, will rise once the Fed moves to raise rates, likely to record highs,” said Mark Zandi, chief economist at Moody’s. (CNBC)



Leave a comment