


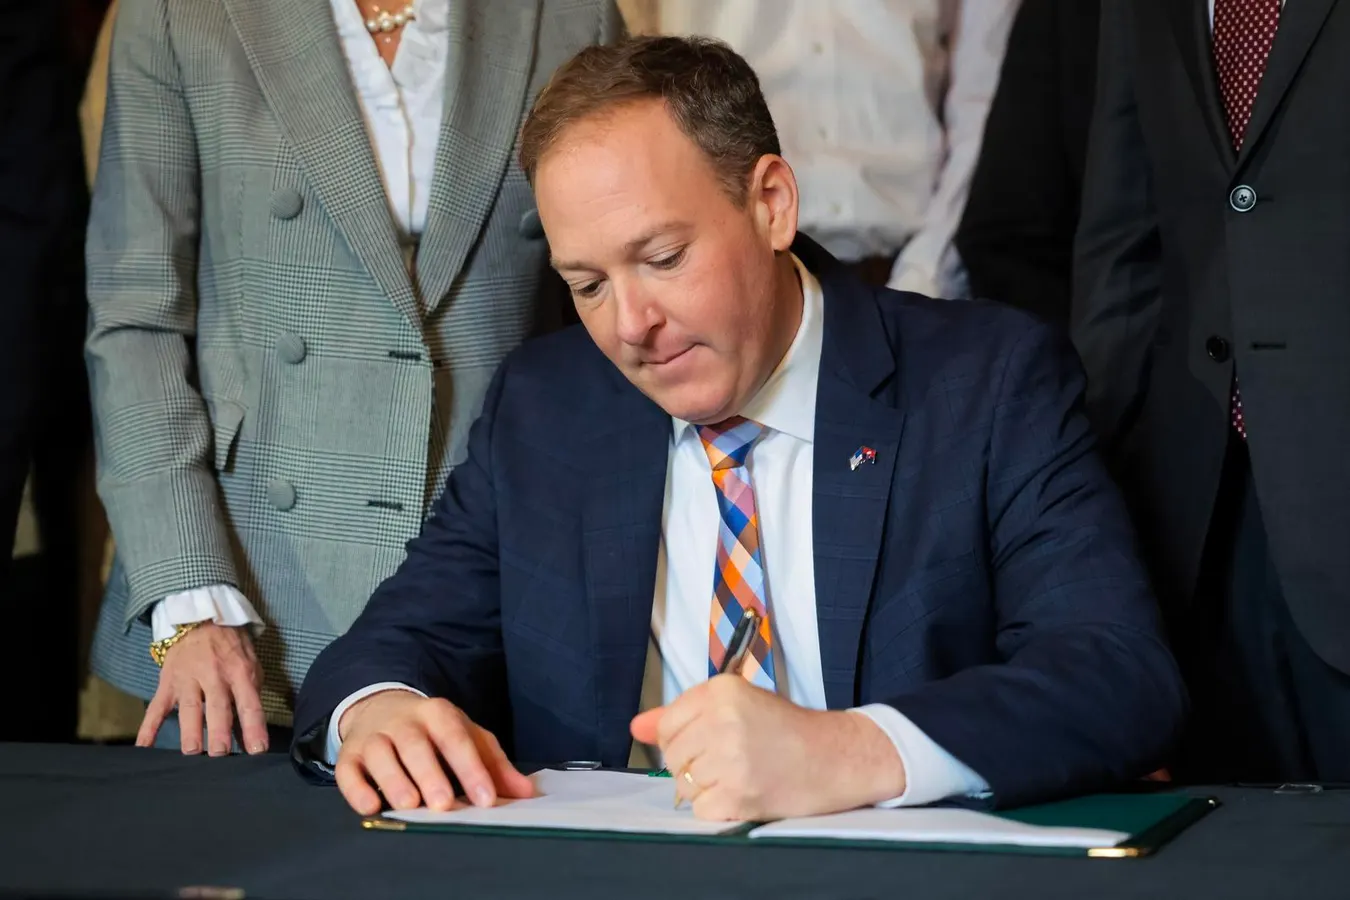

EPA is erasing limits on power plant pollution.
Getty Images
Environmental Protection Agency Administrator Lee Zeldin’s push to roll back greenhouse-gas standards for power plants is being covered mostly as an environmental story. For banks and insurers, that framing misses the point. The rule does not touch financial institutions directly — its real effect runs through their portfolios and counterparties. And the shape of that effect is uneven: it lowers transition risk for fossil-fuel assets in the near term while leaving physical risk — the risk from fires, floods, drought, and storms — fully in place, and in many regions, growing.
What Is Actually Changing
The EPA has already proposed repealing the federal greenhouse-gas standards for fossil-fuel power plants, and reports suggest the agency is preparing to go further, arguing that greenhouse gases from power plants do not endanger human health or the environment under the Clean Air Act. Separately, in October 2025, the Federal Reserve, FDIC, and OCC withdrew their 2023 climate-risk management principles for large banks, saying existing safety-and-soundness rules were sufficient. Two deregulatory moves, one direction: climate exposure is being pulled back into “ordinary” credit, market, and operational risk rather than treated as its own supervisory category.
The Quick Summary
EPA’s rule affects banks’ and insurers’ portfolios and counterparties.
MRV
Banks: Better Borrower Economics Today, Worse Collateral Tomorrow
The near-term logic is simple. If coal and gas plants no longer face stringent carbon standards, they get cheaper to run, and new gas generation gets easier to finance. Banks lend directly into that chain — power plants, gas infrastructure, pipelines, utilities, commercial real estate, and increasingly, the data centers and power buildout behind AI. Lower regulatory risk generally means better borrower economics and, on paper, better credit quality.
But this is where the story turns. The single most important line in this whole analysis is that climate change functions as a direct credit-quality problem for borrowers in fire-, drought-, and flood-exposed regions of the U.S. — regardless of what happens to federal carbon rules. The Federal Reserve has mapped the transmission mechanism explicitly: a climate event damages property or business operations, collateral values fall, borrowers default at higher rates, and banks absorb the credit losses. Hurricanes, wildfires, floods, heat waves, droughts, and sea-level rise are the named channels.
Picture a bank holding $100 billion in mortgages, $30 billion in commercial real estate, $20 billion in corporate loans, and $10 billion in infrastructure loans. The EPA rule does not touch any of that directly. But as physical risk makes certain regions harder or costlier to insure, the collateral behind those loans erodes quietly. That creates a feedback loop worth tracking closely:
Climate change impacts banks’ credit risk exposure.
MRV
For banks with concentrated exposure to wildfire zones in the West, drought-stressed agricultural regions, or flood- and hurricane-prone coastlines, this is arguably a bigger driver of future losses than anything happening at the EPA. Climate risk, in other words, is migrating from an “environmental” line item into a straightforward credit-underwriting problem — borrowers in these regions are becoming structurally weaker credits, whether or not lenders have caught up to that reality in pricing.
Insurers: A Split Personality
Insurers split into two very different exposure profiles.
Life insurers — MetLife, Prudential, Athene, Corebridge, Lincoln, Global Atlantic, Equitable — are primarily asset-side players. The NAIC notes that transition risk matters more for life insurers because they typically aren’t insuring physical property; their exposure runs through investment portfolios: utility bonds, energy private credit, infrastructure debt, project finance, CLOs holding energy loans, and fossil-fuel equity. Deregulation reduces the odds of a sudden regulatory hit to those assets — a genuine near-term benefit.
Property and Casualty insurers face the opposite problem. Their core exposure is the insured property itself — homes, commercial buildings, factories, vehicles, farmland — sitting directly in the path of physical climate risk. Former Fed Vice Chair Michael Barr pointed to wildfires and flooding as clear evidence of stress building in P&C insurance markets. So a single policy can cut transition risk in an insurer’s bond portfolio while simultaneously increasing the physical risk embedded in its underwriting book.
The Mortgage Market is the Transmission Belt to Watch
This is probably the most consequential bank/insurer linkage. Take a $1 million home with a $750,000 mortgage and $250,000 in equity. If wildfire, flood, or hurricane exposure makes the property hard to insure, annual premiums might climb from $3,000 to $8,000 to $15,000. The buyer pool shrinks, and the home’s value slips to $850,000. The bank’s cushion — the gap between loan value and property value — falls from $250,000 to $100,000. Push the property value down further and the loan-to-value ratio deteriorates outright. This is exactly how a regional climate problem becomes a conventional credit problem on a bank’s books, county by county, without a single new regulation being written.
Private Credit and CLOs: Exposure Hiding a Few Layers Down
Bank deregulation is likely to pull more capital into gas generation, pipelines, LNG, and data-center power through private credit and project finance. For insurers invested in those funds, the near-term picture is attractive — less transition risk, often higher yield. The longer-term picture is a growing concentration in assets tied to a single energy-policy regime and to physical climate exposure that’s harder to mark or exit than public securities.
Collateralized Loan Obligations (CLOs) extend the chain further. A life insurer may hold no direct fossil-fuel assets, yet own a CLO tranche funded by leveraged loans to an energy borrower — several steps removed from the underlying exposure and easy to miss in a simple asset-allocation review.
The Bigger Picture
Zeldin’s EPA move does not erase climate risk from the financial system — it reshuffles it. Transition risk eases for fossil-fuel companies, utilities, power generators, the banks that finance them, and the insurers holding their securities. Physical risk does not ease at all, and continues to build in homes, commercial real estate, mortgage books, P&C underwriting portfolios, municipal finances, and bank collateral — concentrated precisely in the fire, drought, and flood corridors of the country. The Fed’s own framing captures it best: climate risk doesn’t stay a separate category for long. It shows up as credit risk, market risk, liquidity risk — the ordinary kind, just distributed across a different map than it was five years ago.



Leave a comment